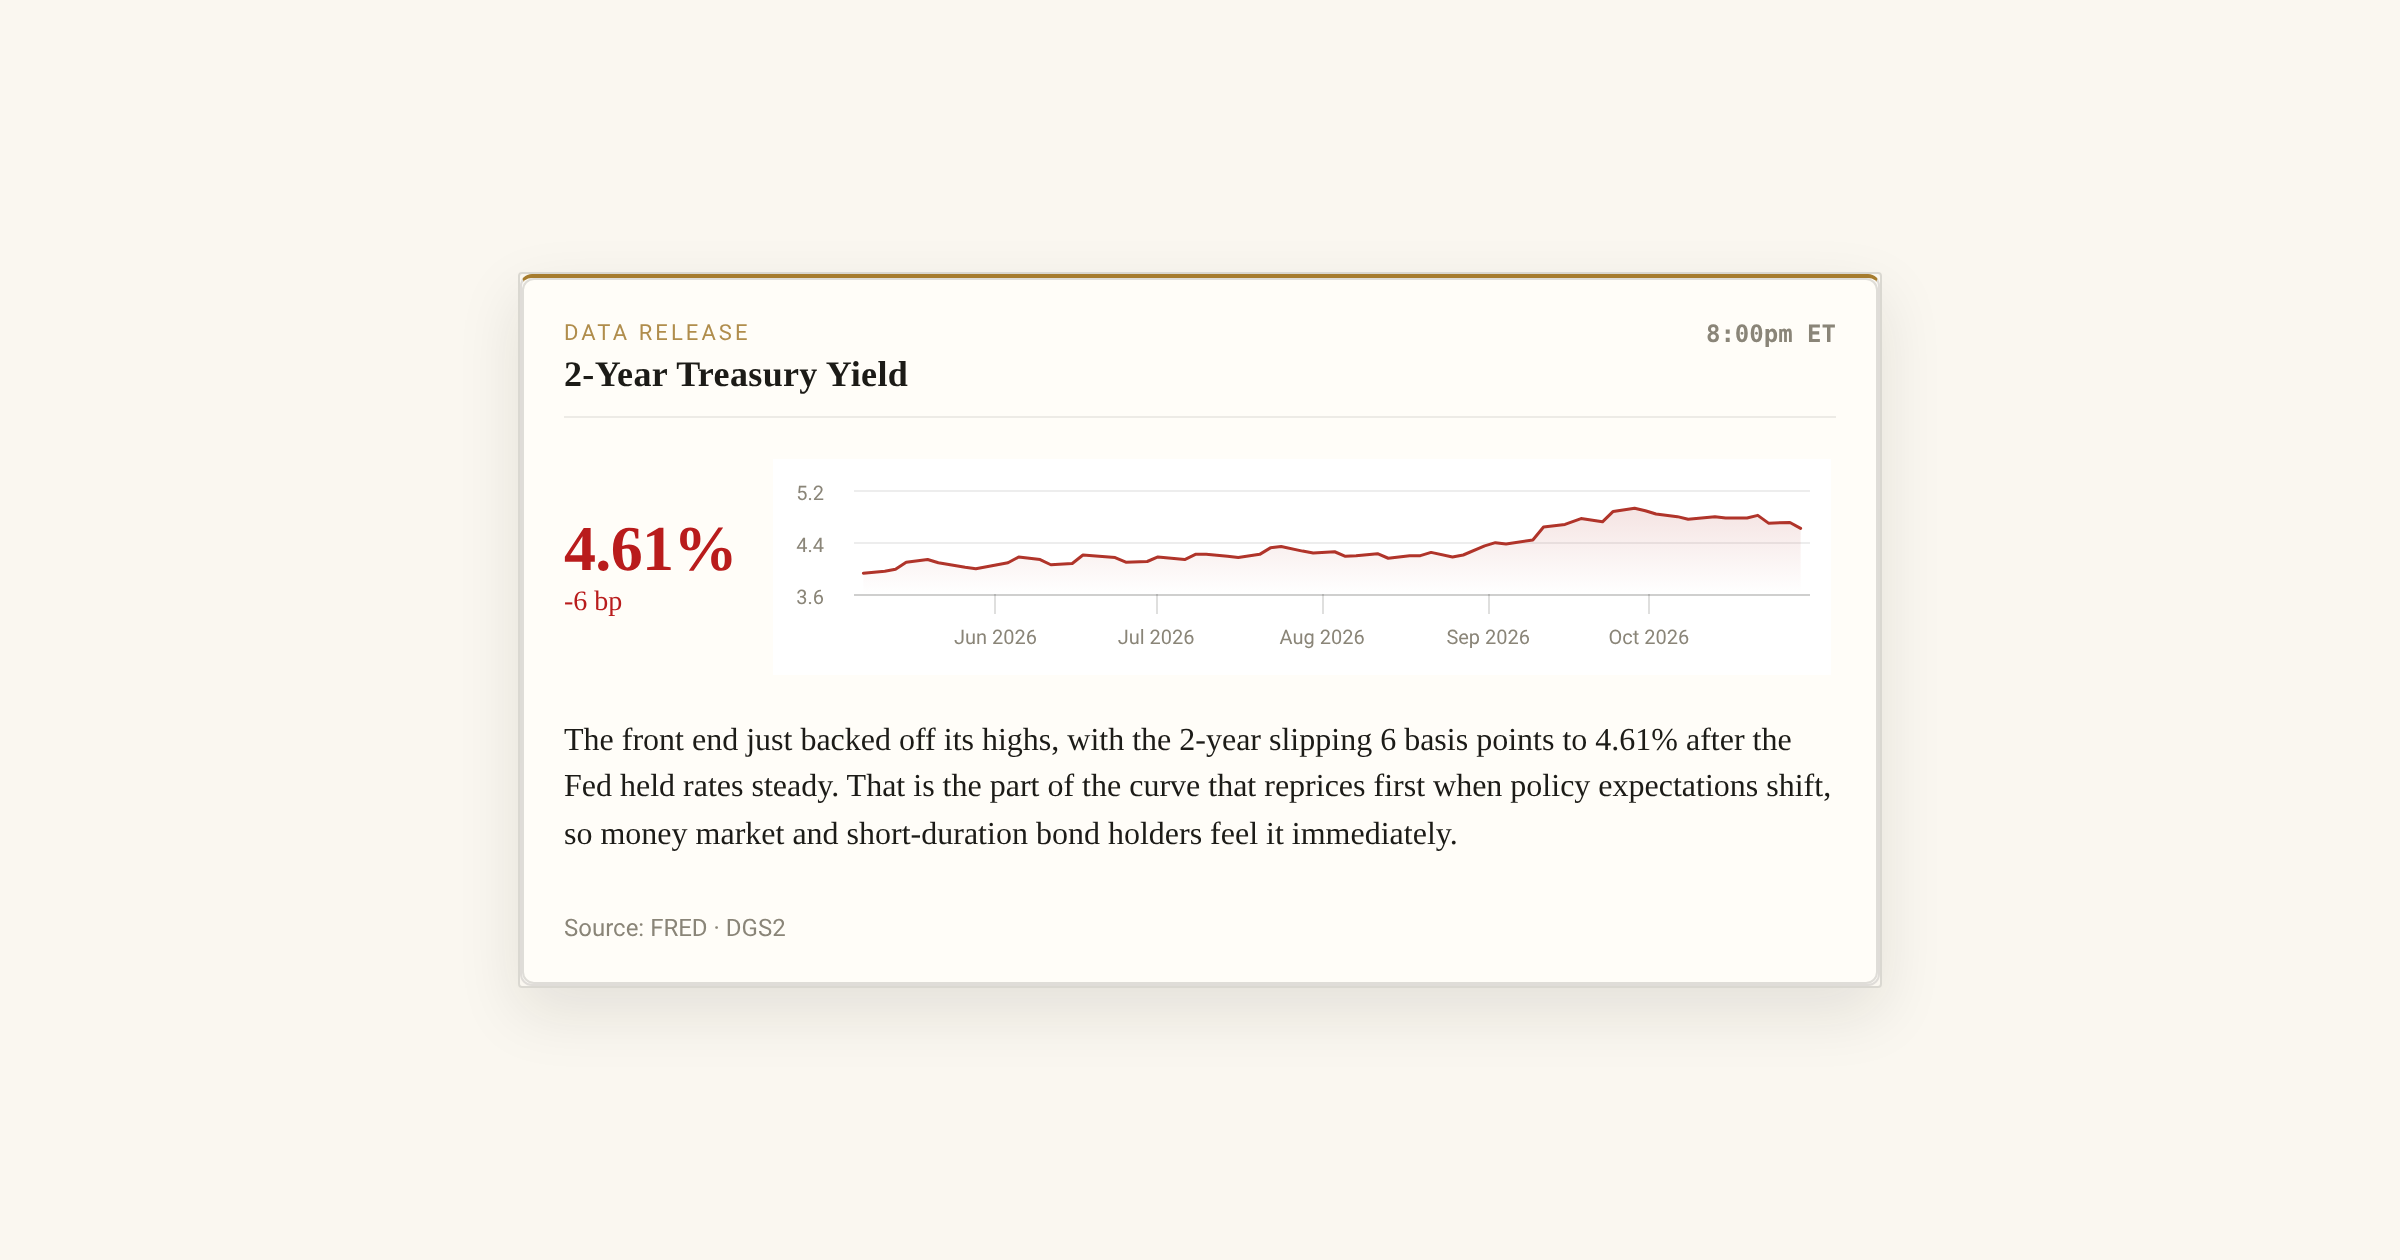
The front end just backed off its highs, with the 2-year slipping 6 basis points to 4.61% after the Fed held rates steady. That is the part of the curve that reprices first when policy expectations shift, so money market and short-duration bond holders feel it immediately. The 2-year Treasury yield is the bond market's most direct read on where traders think the Fed will set short-term rates over the next couple of years. When it falls 6 basis points in a single session to 4.61%, the market is quietly marking down its expectations for how long policy stays restrictive. The Fed's decision to hold rates steady was the immediate trigger.
Mostramos la idea principal publicamente. Crea una cuenta gratis para seguir leyendo el articulo completo, guardarlo, comentarlo y conectarlo con contexto de mercados y OSINT.